

Nigerians don’t spend money the same way. Some people see an alert and start paying bills that may have been allocated for school fees, rent, and other expenses. Others see their alert and think, “It’s time to ball.”
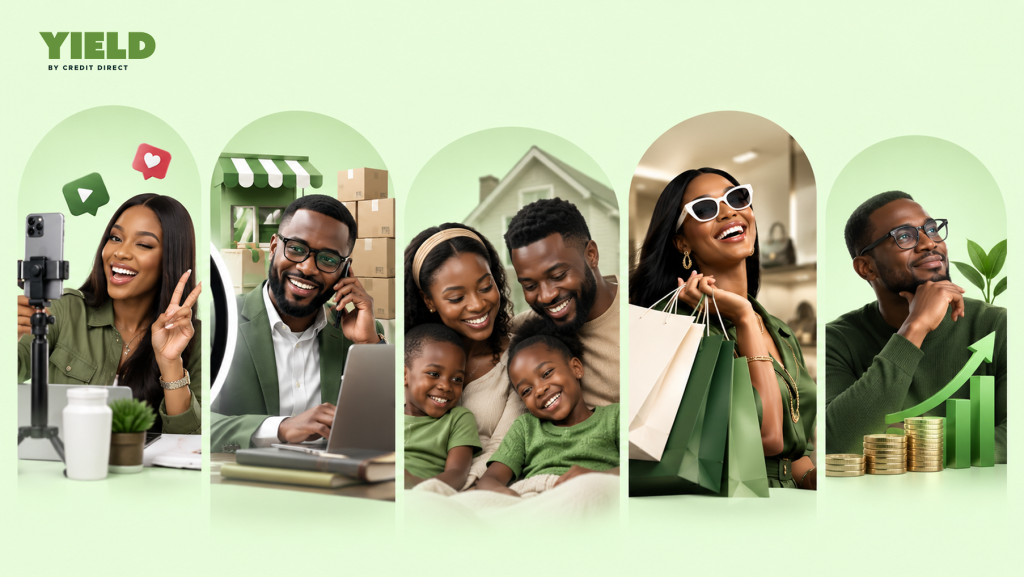
During the Wealth Lab session by Yield by Credit Direct at NairaLife, five different money personas showed just how differently Nigerians approach their income. So, which one are you?
The Social Media Influencer
This person’s face is the business, and their income comes from brand deals, paid posts and the occasional ambassador cheque. The only problem? The money lands whenever it lands.
No dependents yet, no serious debt, just a nice apartment on the better side of the Mainland or on the Island because, honestly, the address matters when half your content is shot there.
But being the brand comes with its own bills. There are the outfits, self-care, nice restaurants, outings, aso ebi, and, of course, the Detty December content that they simply cannot miss. For this person, looking good isn’t just vanity. It’s part of the job.
The Entrepreneur
This person’s salary is basically “it depends.” They run their own thing, maybe a small business, freelance, sell products online, or somehow manage to do all three.
Some months are giving “soft life season”, and others are giving “Let me breathe first.” There’s no fixed payday and no HR to remind them about salary. If a client delays payment, a customer cancels an order, or business is slow, this person feels it immediately. And when they receive extra money, they may not think about phone upgrades, taking a trip or finally buying that big purchase. They have to think about next month.
They have to restock, pay suppliers or artisans, run ads, sort out data and transport, and sometimes an employee or two are waiting for their salary.
The Family Person
This person doesn’t even get the chance to enjoy the zeros in their paycheck because responsibilities are always knocking. They are everybody’s emergency contact, especially when money is involved.
Their parents are retired, so sending money home every month is already part of the budget. They also have a younger sibling to support. Nobody needs to ask. Most importantly, they have their own household to run. This includes school runs, food, fuel for the car and generator, and the random expenses that never seem to end. The Family Person is usually big on responsibility. Their money isn’t just their money because people depend on them.
They’d love to invest more and actually build something for themselves, but there’s always someone who needs help. And saying “I don’t have” isn’t always as easy as it sounds.
The Big Spender
This person earns well. On paper, this person is doing alright. The salary is decent, but somehow, the money disappears before the month is over.
It starts innocently enough with “It’s just ₦50k to enjoy the present.” Then another ₦20k here, ₦30k there. There’s always an outing to attend, a new restaurant to try, a random online purchase, or something to upgrade that was perfectly fine before. Even if the phone still works, they want a newer one. Their wardrobe is full; somehow there’s still nothing to wear. They’re the person ordering food instead of cooking and satisfying cravings because they don’t want to stress themselves.
Before they know it, all the small-small spending has dipped deep into their salary. Then they ask themselves, “What did I actually spend all this money on?” and “How come I haven’t saved up to XYZ?”
The Investor
For this person, investing is already part of the plan. They have a fixed amount and don’t wait for money to remain before investing. This person has watched enough videos and read enough books about investing to start using words like “portfolio diversification”.
They’ve simply realised that leaving all their money in a regular account isn’t exactly making it work. At this point, budgeting isn’t really their problem anymore. They are asking questions like: Should I put more money into an investment that can earn more over time? Should I keep some cash easily accessible? Should I take on more risk for potentially higher returns or play it safe?
They’re also the person who will read the terms and conditions before putting money anywhere. Because they’ve worked too hard to earn and build their funds to start making random financial decisions because someone on Twitter said, “Trust me, bro.”
So, Who’s Actually Doing It Right?
None of them. And all of them.
There isn’t one correct way to spend money. The Family Man has responsibilities. The Influencer needs to build a career. The Entrepreneur needs capital and plans to scale. The Big Spender wants to enjoy life and have emergency funds. The Investor wants to keep growing wealth.
The real question is “Does the way you’re using your money match what you want your money to do?”
This is where Yield by Credit Direct supports your goals. Whichever persona(s) you identify with, the goal is to make sure your money habits are helping you get where you want to go. Yield by Credit Direct gives you options to do just that, with Target Yield for specific goals, Flex Yield when you want access to your money while it grows, and Fixed Yield that offers up to 21% per annum, depending on the tenure.